


TRY OUR GROWTH SCANNER


Venture Capital Benchmark Q3 2026
US, Europe, and Latin America
TheVentureCity's VC Benchmark is a quarterly venture capital report on the US, Europe and Latin America. In Q3 2026, global deal value reached $170.8B across 8,368 deals, the fewest since 2017. Key trends: AI agents, agent security, Physical AI and LatAm.
VC Activity

Q3 2026 kept the pattern of fewer, bigger checks: global deal value hit $170.8B (down 29% QoQ, up 43% YoY) on 8,368 deals, the fewest since Q3 2017. Year to date, value is up 91% on 2025 but deal count is down 10%, driven by a few huge AI rounds rather than more funded companies. North America (US and Canada) drove the QoQ drop, down 40% to $99.2B, but still accounted for 58% of the global total. Europe posted its highest value since Q2 2022 ($28.3B) on its fewest deals since 2016 (1,476), lifting its average deal size to about $19M from $13M in Q2. LatAm rebounded to $1.9B but is still down 17% year to date. Together, the 3 regions this report covers took $129.4B, 76% of global deal value.


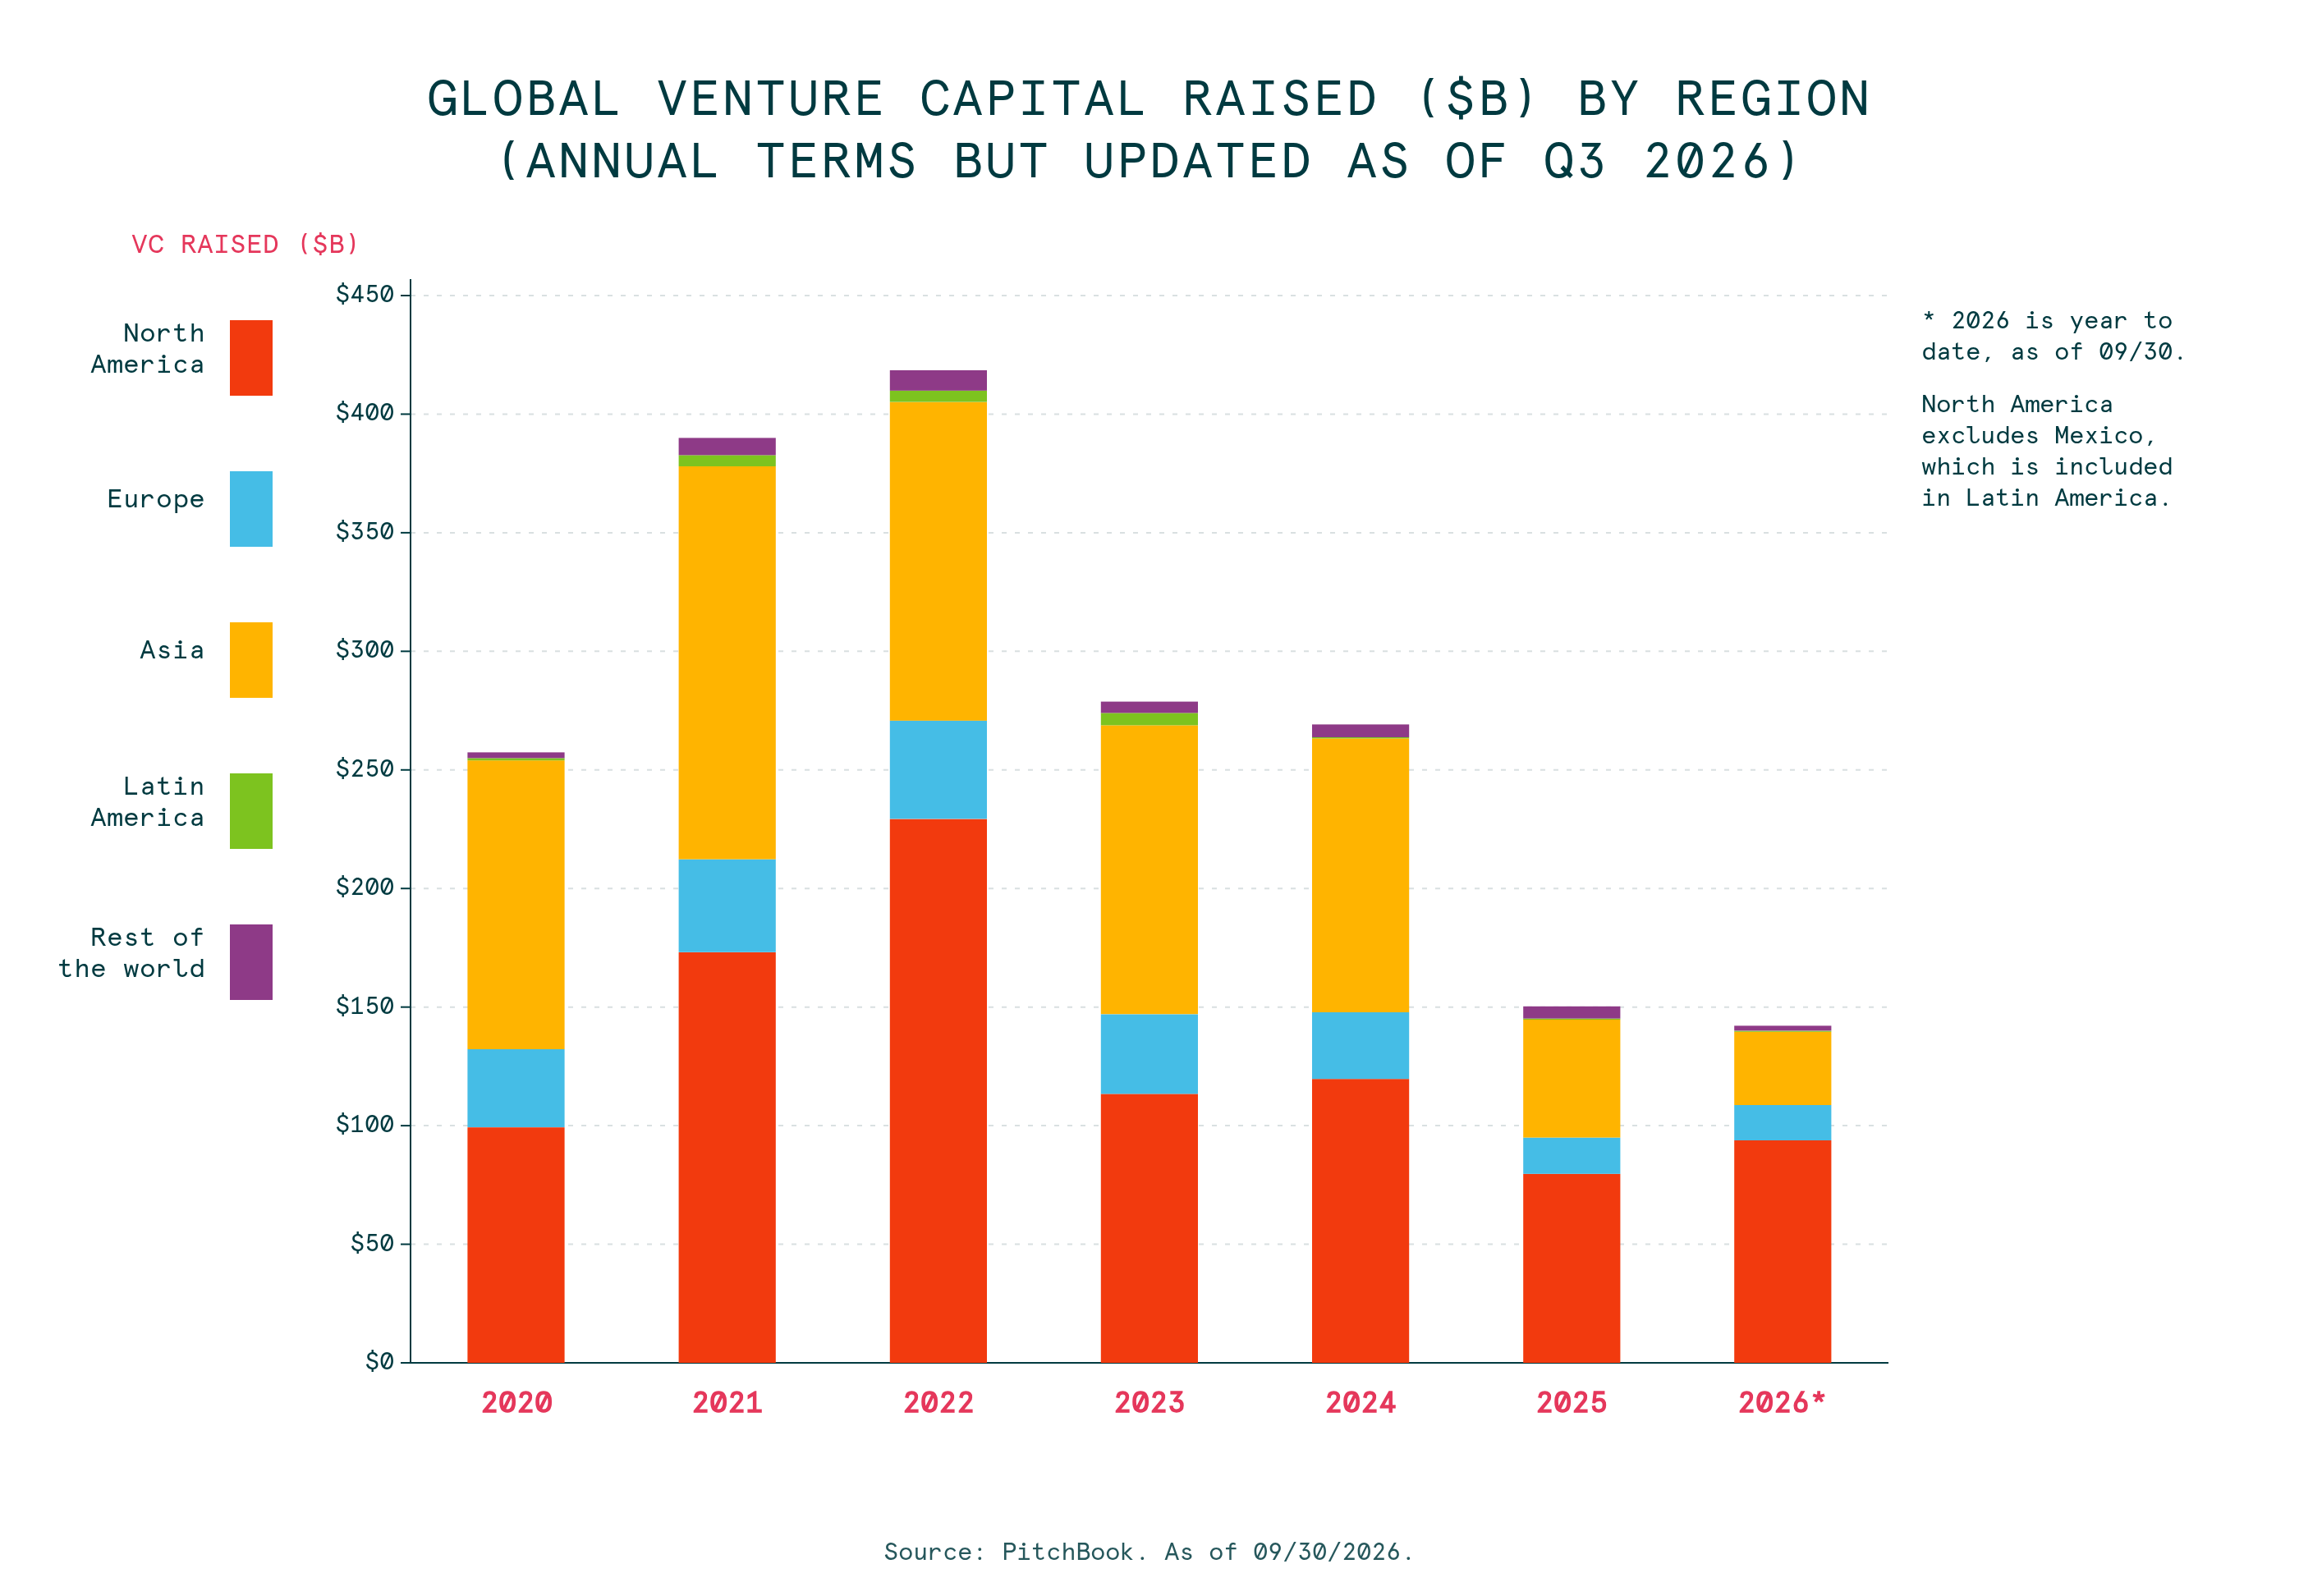
Fundraising is on track to beat 2025 with a quarter still to go. Global VC raised $142.1B through Q3 2026, already 95% of 2025's full-year $150.3B. North America drove it with $93.8B, 66% of the total and already 18% above its full 2025 figure of $79.7B. Europe raised $14.9B, already 97% of its 2025 total ($15.3B), and LatAm funds raised $0.4B, close to last year's $0.5B. Across the 3 regions this report covers, funds have raised $109.1B so far in 2026, more than in all of 2025 ($95.5B) and 77% of the global total. Still, this is far from the 2021-2022 peak, when North America alone raised more than $170B a year. The rebound is concentrated in North America rather than broad-based.


Exits came back to normal levels after Q2's SpaceX spike. Global exit value was $185.2B in Q3, down 90% QoQ from Q2's ~$1.92T but up 6% YoY. Excluding SpaceX's IPO, Q2 was roughly $146B, so the underlying trend is up about 27% QoQ. North America led with $113.8B, up 32% YoY, Europe rose 14% QoQ to $21.0B and LatAm exits stayed small at $0.5B. Exit count tells a weaker story: 666 exits globally, down 23% QoQ and 24% YoY and the lowest since Q2 2020. The 3 regions this report covers accounted for 518 exits, down from 686 in Q2, and $135.3B, 73% of global exit value. Year to date, exit count is down 13% on 2025. Fewer companies are getting out, but the ones that do are larger.


Source:pitchbook
01
Personal Agents Are Booming, and They're Your Next Customers
Personal agents went mainstream in Q3, and they arrived ready to buy. Meta's Muse hit No. 1 on the App Store ten days after launch, OpenAI followed with Dots, and Instinct went from a $2.5B to a $10B valuation in a month. With Stripe's Link wallet inside Muse, products now need to be readable, verifiable and payable by an agent.


02
Agents Need Security, and the Platforms Are Buying It
Companies are deploying AI agents faster than they can track them, and the large platforms chose to buy rather than build: Palo Alto Networks, Fortinet, Okta and Keyfactor all acquired agent-security or AI-identity startups this quarter. Identity is the weak point, the space where our portfolio company Constella works. For security founders, that means a shorter path to a strategic exit.


03
Physical AI Takes the Biggest Checks
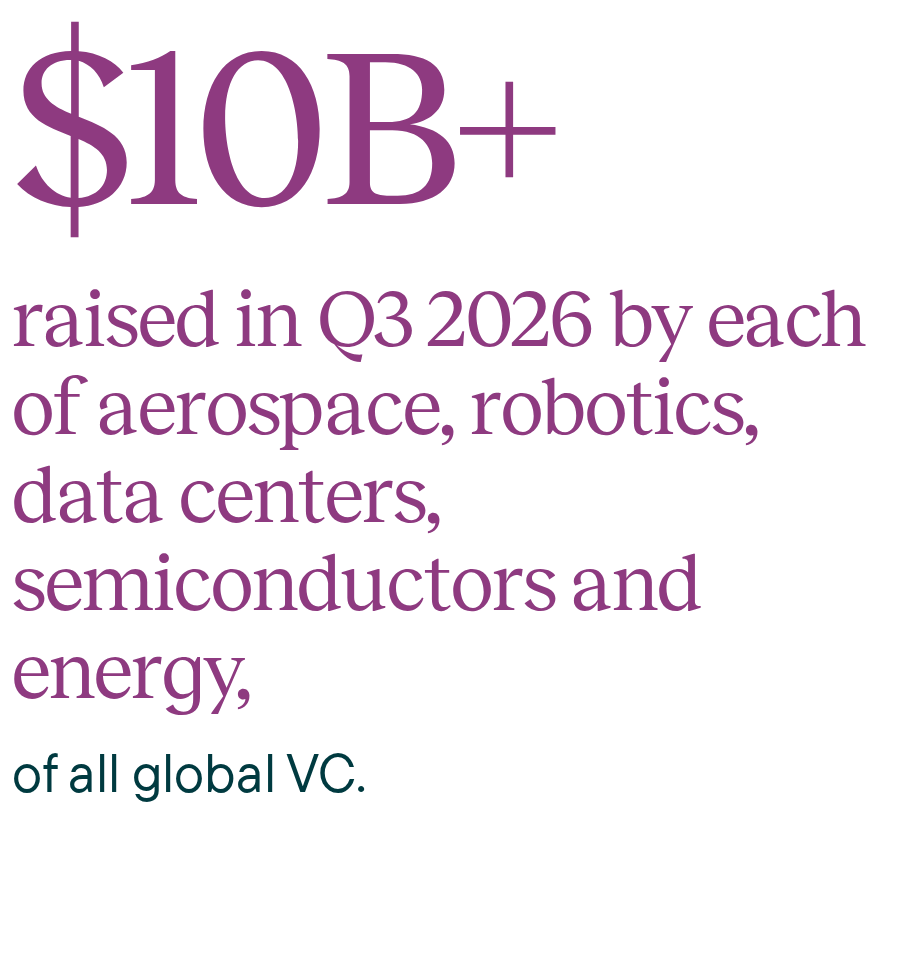
Investors kept backing companies that build atoms, the Physical AI shift we anticipated in our Q4 2025 report: aerospace, robotics, data centers, semiconductors and energy each raised more than $10B in Q3. For early-stage investors, the entry point is the software that makes these assets cheaper to run, the bet behind Plexigrid, our portfolio company for the power grid.


04
Silicon Valley Rediscovers LatAm
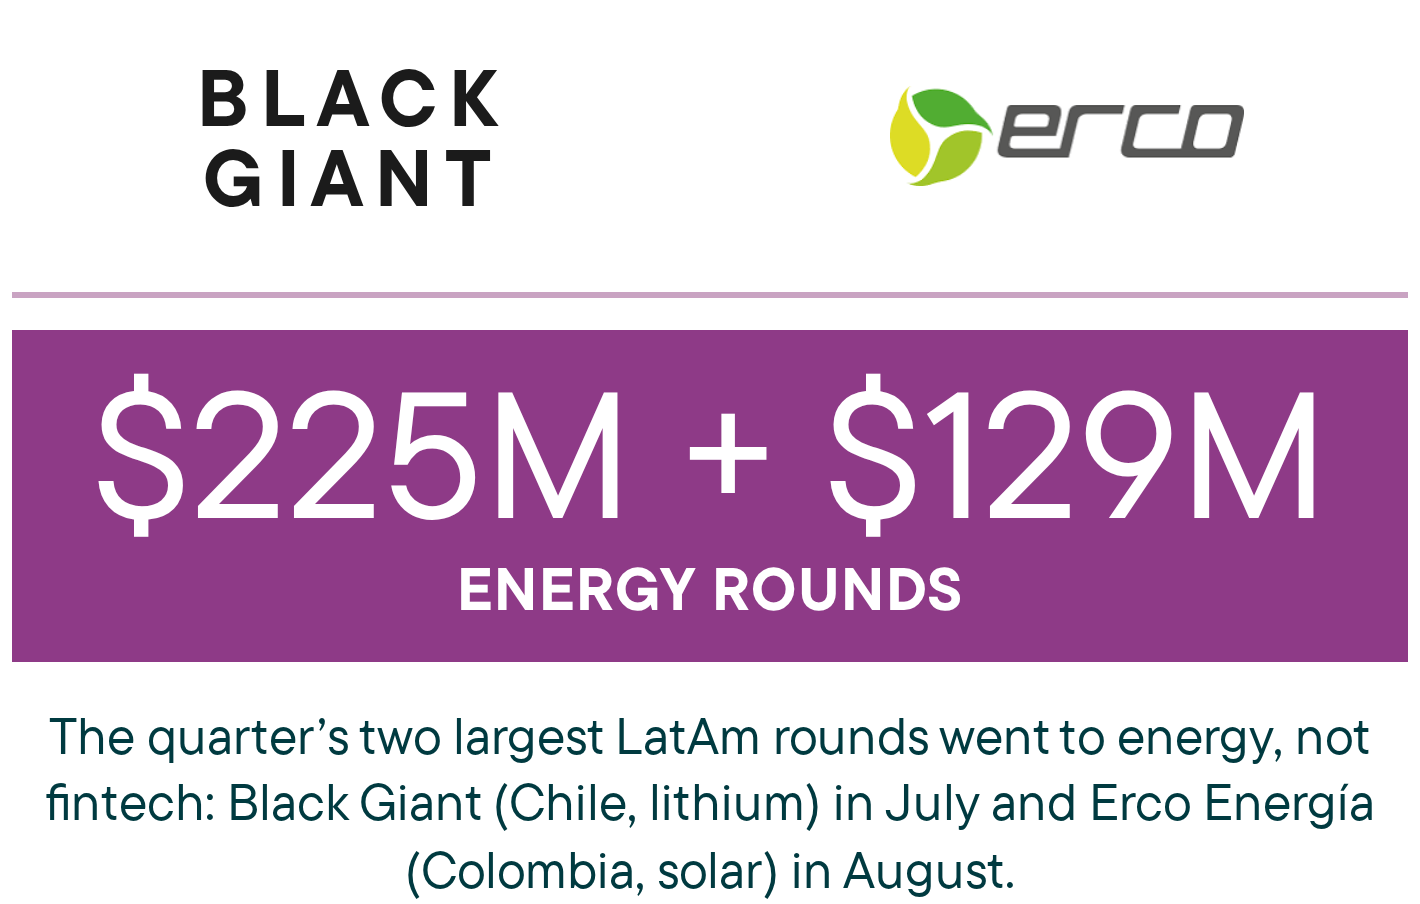
US investors are coming back to Latin America: Sequoia, Founders Fund, NEA and Battery all backed Brazilian startups, and per Endeavor Catalyst, international VCs were more active in the region in 2026 so far than in 2024 and 2025 combined. The money follows founders building global companies from LatAm, including in Argentina, where our portfolio company Belo runs a stablecoin wallet. Still a turn, not a boom: LatAm deal value is down 17% year to date.


Looking ahead
Is AI Becoming a Religion?
Liquidity Keeps Coming From M&A, Not IPOs
Agents Get Bought From More Than One Budget
The AI Lab IPOs Will Reset Private Valuations


